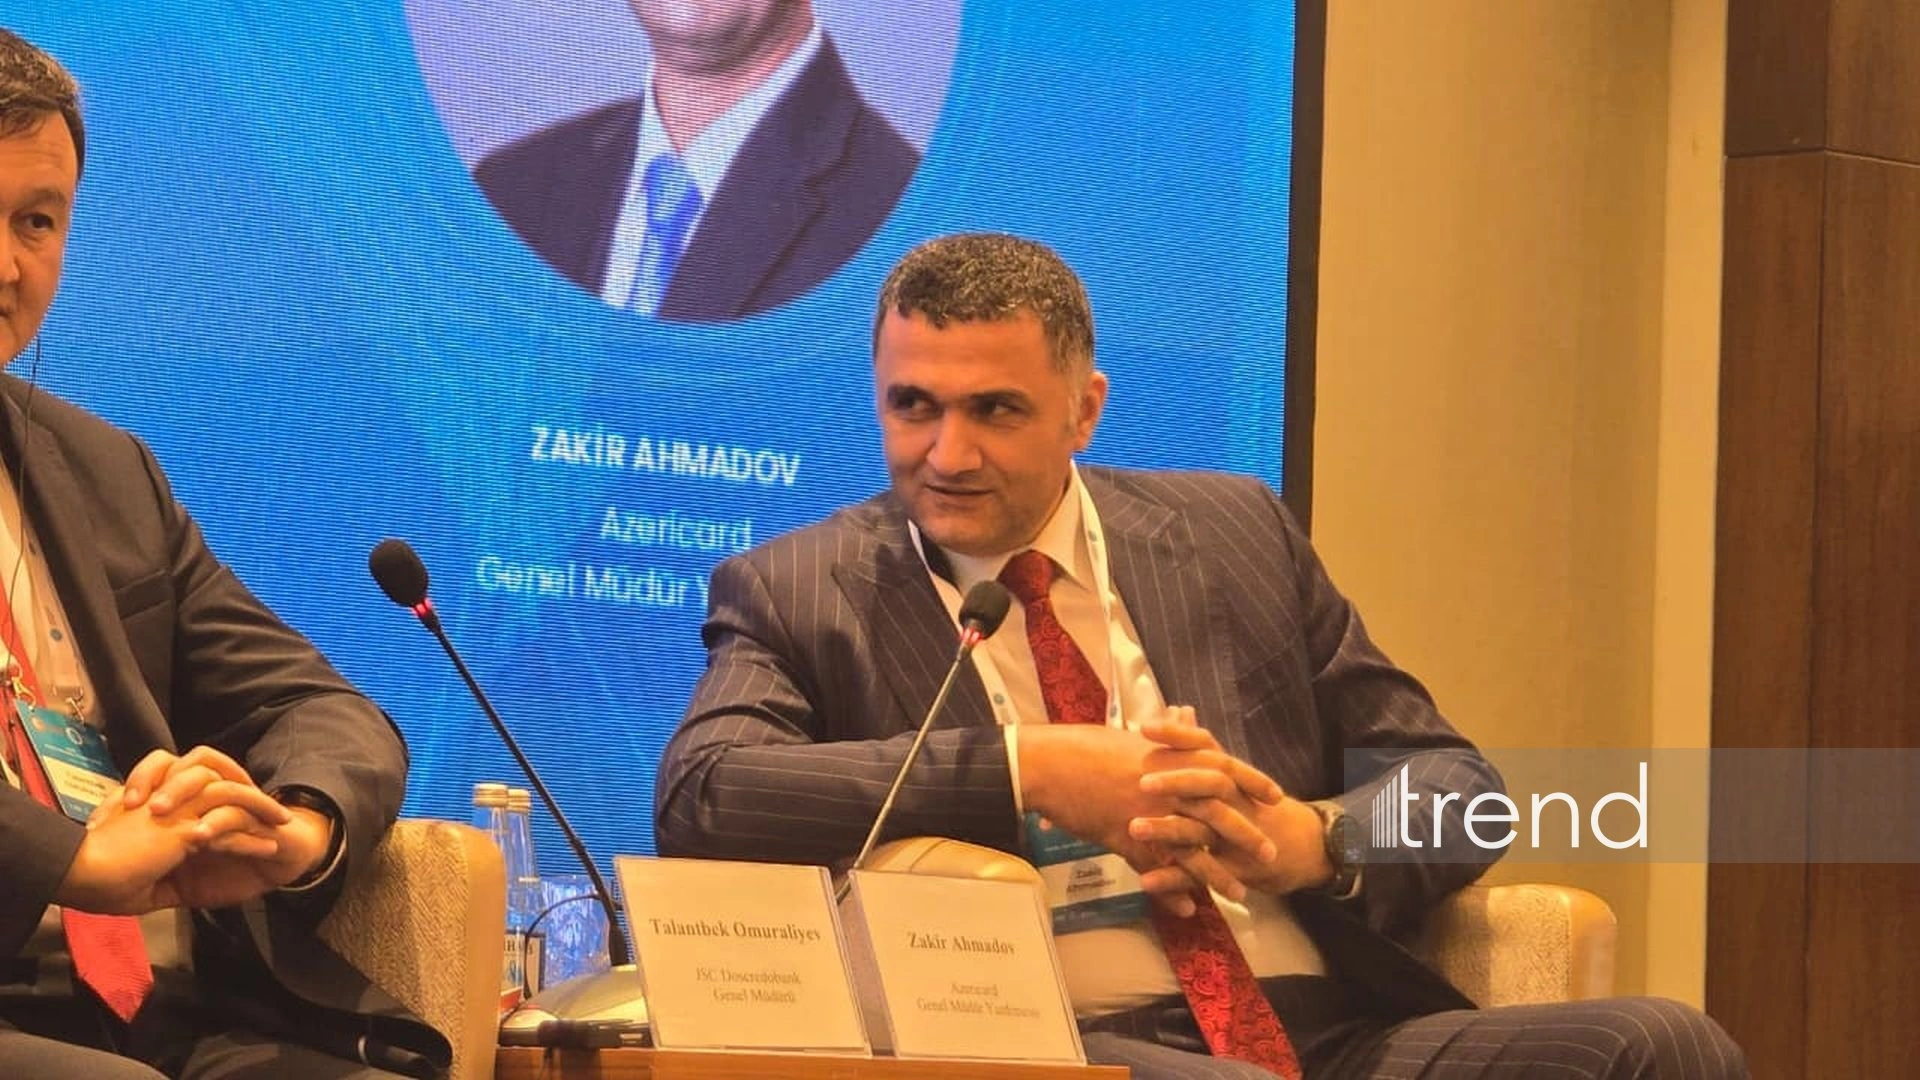
BAKU, Azerbaijan, October 13. A new model
designed to improve the assessment of bank customers’
creditworthiness and reduce the risk of late loan repayments has
been developed in Azerbaijan in cooperation with Mastercard,
Azericard Deputy CEO Zakir Ahmedov said on Tuesday at the Baku
Fintech Sector Trade Mission Program, Trend’s correspondent reports from the
event.
According to Ahmedov, around 70% of Azerbaijan’s population has
a credit history, with the relevant information collected by the
Azerbaijan Credit Bureau (ACB). However, people without a credit
history also use bank cards, and their financial transactions can
provide insights into their income, spending and consumer
habits.
“About 70% of people in Azerbaijan have a credit history. The
others do not, but they also have bank cards and conduct
transactions through them. These transactions can provide
information about customers’ income, expenses and the areas on
which they primarily spend their money,” Ahmedov said.
He noted that these data create new opportunities to assess the
creditworthiness of people with no credit history or a limited
borrowing record.
According to the company representative, the model developed
jointly with Mastercard analyzes various factors to estimate the
likelihood that customers will make their loan payments on time. It
uses the SHAP (SHapley Additive exPlanations) approach to explain
how individual factors contribute to a credit-risk assessment.
“Using this model, we can identify the factors that influence
whether a customer is a reliable or risky borrower. These include
previous loan delinquencies, the number of loans a customer has,
income, age, gender and other indicators,” he said.
Ahmedov noted that approximately 1,250 indicators were initially
considered. Following the analysis, 56 key indicators were selected
for the model to assess each customer’s risk of late repayment.
He added that delays on previous loans negatively affect a
customer’s risk profile. By analyzing these and other factors
together, the model provides banks with additional information to
support lending decisions.
According to Ahmedov, the model was trained on data from the
first three quarters of 2025 and subsequently tested using data
from the following quarter. Its performance was compared with that
of credit-scoring systems currently used by banks.
“Based on the test results, our model can perform 3%–7% better
than the existing scoring models used by banks,” he said.
He added that the tests also assessed the model’s ability to
identify late repayments among customers considered eligible for
loans. According to the figures he presented, 0.3% of customers
recommended for lending by the new model subsequently fell into
arrears, compared with 16% of customers who received loans under
existing bank assessments.
Ahmedov said the model is expected to be presented to banks in
the near future for use in their credit-risk assessment
processes.
Its adoption could help banks assess customers with limited
credit histories more comprehensively, improve lending decisions
and identify potential repayment risks in advance.