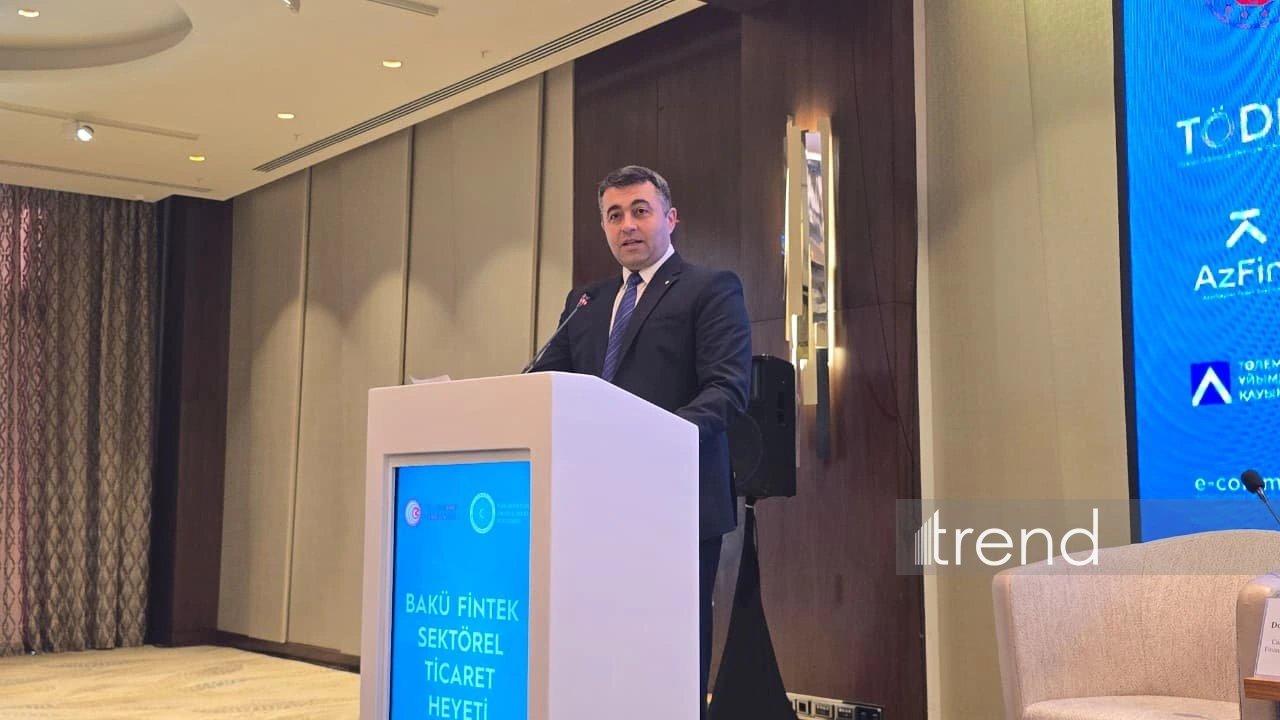
BAKU, Azerbaijan, October 13. Turkic states
should begin implementing joint fintech solutions through pilot
projects in two or more countries and then expand successful
practices to other markets, the Chairman of the Board of the
Azerbaijan Fintech Association, Edgar Abdullayev, said during a
fintech mission involving representatives of Turkic states,
organized by the Turkic States Fintech Alliance (TÜRKFİN) in Baku,
Trend's correspondent
reports from the event.
"Türkiye is one of the largest and most developed fintech
markets in the region. As of the end of last year, 24 payment
organizations and 62 e-money institutions were operating under the
supervision of the Central Bank of Türkiye. Türkiye’s experience,
particularly in the areas of acquiring, e-money, e-wallets, open
banking, and the commercialization of digital payment products,
holds great practical value for the region,” he noted.
According to him, by the end of 2025, the number of bank cards
issued in Uzbekistan exceeded 68 million, and the number of active
POS terminals reached 430,000.
“In Kazakhstan, payment organizations have become significant
players in the economy. In 2024, the total volume of transactions
processed by payment organizations reached 8.2 trillion tenge. In
the second quarter of 2026, the volume of transactions using
electronic money exceeded 684 billion tenge,” Abdullayev added.
In Kyrgyzstan, he said, the legal and technological
infrastructure for electronic money, QR payments, and API-based
financial platforms is steadily developing.
“Although the level of development and models in our countries
differ, we are moving in the same direction,” he said.
In this regard, Abdullayev proposed moving from conferences and
reciprocal visits to practical cooperation in five areas.
“The first area is ensuring the interoperability of national
payment systems, instant payment systems (IPS), and QR
infrastructure. We need to work on creating a common payment
platform and ecosystem for the Turkic states so that electronic
money accounts, wallets, and bank accounts opened in one country
can be used seamlessly and conveniently in other countries in the
region.
The second priority is to develop common technical standards and
approaches to APIs, as well as to work on ISO 20022 standards, open
banking, QR payments, and digital identification. “This will
significantly reduce the costs of cross-border integration,” he
said.
The third area, as he put it, is regulatory passporting, which
provides for the mutual recognition of licenses and simplifies
access to other countries’ markets.
“I’m not saying that a single license should be in effect in all
Turkic states starting tomorrow. This is a long-term process that
must, of course, take into account each country’s sovereign
authority in the regulatory sphere. However, at the very least, if
an electronic money institution or payment organization licensed in
one Turkic country enters the market of another Turkic country, the
licensing process could be simpler and more flexible,” he
explained.
The fourth area is cooperation in the fields of anti-money
laundering (AML), know-your-customer (KYC), combating fraud, and
ensuring cybersecurity.
“Unfortunately, just as payments know no borders, fraud and
financial crimes also know no borders. And we, the Turkic states,
can fight them together,” Abdullayev noted.
“The fifth area of focus is the creation of a common regulatory
sandbox and the implementation of regional pilot projects. Rather
than rolling out the new model simultaneously in all five
countries, it makes more sense to start with pilot projects in two
or more countries and then expand the successful model to other
markets,” he said.
The “Baku Fintech Sector Trade Mission” program, organized by
the Turkic States Fintech Alliance (TÜRKFİN), is taking place in
Baku. Representatives from the financial and fintech sectors of
Azerbaijan, Türkiye, and Kazakhstan are participating in the
event.
The program includes discussions on the prospects for the
development of digital payments in Turkic states, the harmonization
of approaches to the regulation of financial technologies, and new
technological trends in payment systems.